There is increasing pressure on the Bank of England to raise interest rates after inflation rose to 3.1% in August.
Subscribe to our newsletter
Markets are now anticipating “multiple hikes” in interest rates in the coming months due to rising energy prices that are set to rise this winter.
This is likely to have a major impact on anyone remortgaging or purchasing a home in the near future.
The Consumer Price Index (CPI) was 2.9% in July and it was expected that there would be an increase in the August number.
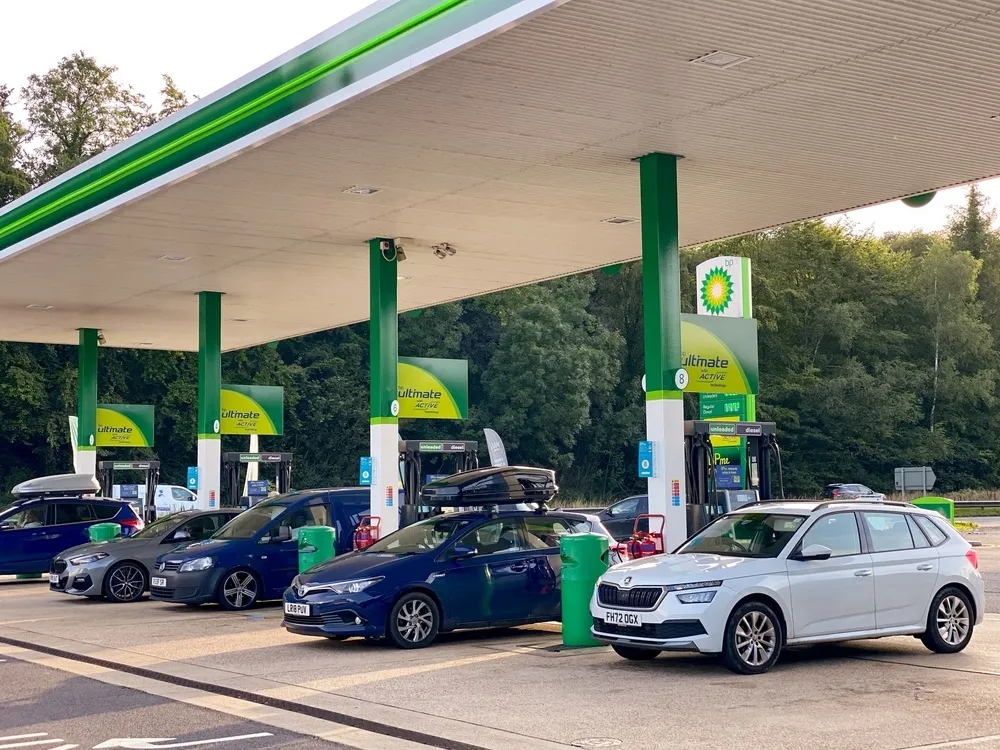
Petrol and diesel were the biggest reason for the rise, but rising energy prices have also had an impact as they feed into household costs.
The component of the index measuring increases in the cost of food and services remained unchanged, highlighting how higher oil prices, resulting from events in Iran, are impacting our domestic finances.
But it is mortgage borrowers who will be most disappointed by today’s inflation figures. Especially since the Bank of England is preparing to set interest rates again tomorrow (Thursday).
Susannah Streeter, chief investment strategist at Wealth Club, believes the bank’s Monetary Policy Committee will still keep interest rates at 3.75% as expected tomorrow. But consumers should prepare for higher borrowing costs after that.
She added: “The biggest shift in expectations is for the coming months, with markets now pricing in multiple increases as the energy shock threatens to keep inflation high.
“This will increase the financial pain for those looking to remortgage or get on the housing ladder.”
What will happen to mortgage rates now?
Today’s inflation data also comes as mortgage lenders hike interest rates with several high street providers raising rates for the second time this week.
With that in mind, along with expectations of rising interest rates, what is your advice for borrowers who are about to take out a mortgage?
David Hollingsworth, associate director at L&C Mortgages, said: “Given the current situation, borrowers should expect mortgage interest rates to remain under upward pressure in the near term.
“Anyone approaching the end of a fixed rate should review their options sooner rather than later. Recent weeks have been a reminder of how quickly the mortgage rate can change when market sentiment changes.”