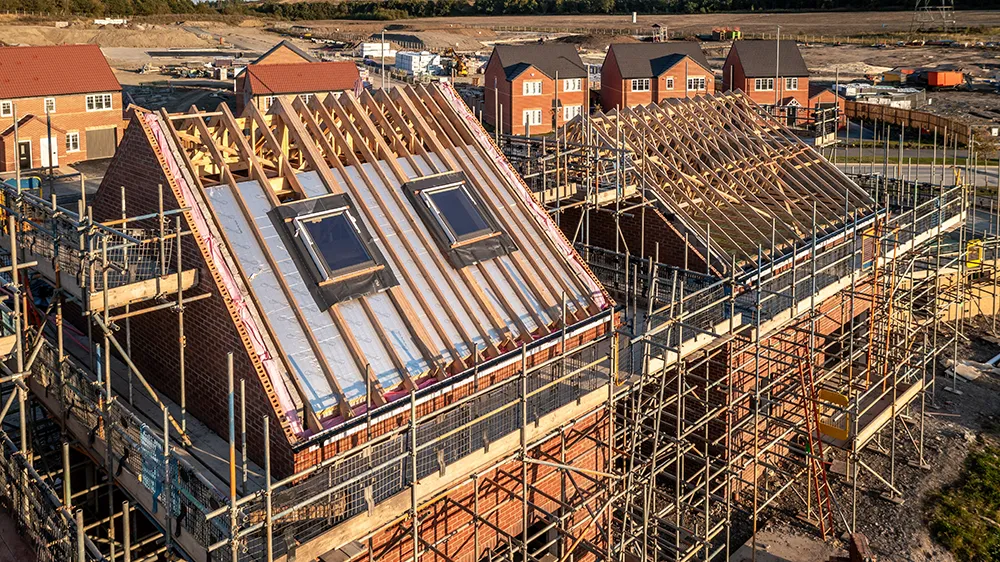

UK construction activity remains under pressure, with new data from Glengan showing a decline in planning consents, contract awards and project starts over the three months to the end of September 2026.
The October edition of Construction Review, published by Glenigan, found that detailed planning approvals were down 16% compared to the previous three months and 28% year-on-year.
Major contract awards fell by 19% quarter-on-quarter, while project starts recorded the largest decline, down 26% compared to the previous three months and 21% compared to the same period last year.
Despite the economic downturn, major contract awards were a notable exception to the broader weakness, rising 25% year-on-year as major schemes progressed towards construction.
These numbers reflect the broader economic challenges facing the sector. While the UK economy continued to grow, official data recorded a 0.5% decline in construction production, underscoring the difficulties facing the industry.
Gillingan’s analysis points to a combination of weak private investment, pressure on household finances, and continuing constraints on the public sector planning system.
Budget cuts and staff shortages continue to impact planning departments, while uncertainty about government spending and borrowing costs affects investment decisions.
Housing construction remains under pressure, with social housing providing a significant counterweight to the decline in private sector activity.
Social housing starts rose 165% year on year to £5 billion, representing 47% of housing starts. In contrast, private dwelling starts fell by 34% to £3.2 billion, while private apartment starts fell by 52% to £1.235 billion.
Rising mortgage costs, falling house prices and pressure on household budgets continue to weigh on private demand, limiting developers’ appetite for new schemes.
Across the wider residential sector, project starts fell by 3% year-on-year, although improved compared to the previous quarter, supported by major projects.
Major contract awards rose by 22% year-on-year, driven by growth in master plans, while detailed planning approvals rose by 2%, indicating a modest improvement in projects underway over the medium term.
Yorkshire and the Humber recorded the highest value for residential construction starts, at £4.427 billion, driven largely by the £4 billion Leeds City Center Heat Network project. London ranked second with £1.2 billion, although it fell by 42%.
The North West recorded growth of 27% to £1.1 billion, while Northern Ireland doubled its residential starts to £296 million. Most other regions saw declines.
While private sector performance remains weak, select public sector markets have shown greater resilience.
Educational planning approvals were up 60% year over year, while community project and facility approvals were up 200%.
The increases indicate that government spending commitments are beginning to translate into activity across the areas of public infrastructure and community service provision.
However, the picture elsewhere remains mixed. Office and industrial projects declined by 55%, reflecting the stronger performance seen in the first half of 2026.
Civil engineering approvals also fell by 70%, raising concerns about the pipeline’s strength in the coming months.
The disparity between public and private sector performance highlights the uneven nature of the current market, with some publicly backed projects progressing while private developers remain cautious.
Alan Wellen, economics director at Glengan, said the rise in contract awards provided some encouragement, but warned it did not yet indicate a broad recovery.
He said: “The rise in awarded contracts shows intent and indicates a return of confidence to parts of the market, and tells us that schemes are being planned and funded, but the work has not yet reached the ground.”
“A very large part of the market is still reliant on a small number of large projects. If one of these falters, the whole sector feels it, and a market reliant on a handful of large schemes is fragile. A real recovery needs to be seen across smaller core schemes, valued at less than £100m, and very few of these projects are currently going ahead.”
Willen said public and private markets face significant challenges, with private developers facing tariffs, taxes and higher interest rates, while uncertainty over public spending commitments remains.
He added, “Developers and contractors are waiting to see what the budget means for families, businesses, and promised government investments.”
“The Budget could be the most significant since Osborne’s austerity Budget and we will be watching it closely to assess its impact on our 2027 recovery outlook.”



